
Insurance for Toy Companies During the Festive Season

Updated: Sep 2

Bringing children's toys to market involves a complex process, from careful design and strict manufacturing to global distribution. Whether you develop educational electronics, produce plastic figurines, or operate retail stores, each stage presents significant risks. Issues such as design flaws, hazardous materials like lead paint, or cyberattacks during peak seasons can lead to litigation, costly recalls, and reputational harm. Securing specialised toy company insurance is crucial to protect your finances, manage risks, and maintain business continuity in the face of unexpected claims.
Key Risks of Toy Companies
Product Defects: Design or manufacturing negligence leading to unsafe toys, such as toxic paint or choking hazards, causing child injuries.
Mass Product Recalls: The sudden need to withdraw entire batches of defective toys globally, incurring massive logistics and public relations expenses.
Physical Store Accidents: Customers slipping or heavy items falling off shelves in busy retail environments, leading to third-party bodily injuries.
Property Damage: Natural disasters, floods, or unexpected fires destroying essential manufacturing equipment, store fixtures, and valuable inventory.
Cyberattacks and Data Breaches: Hackers targeting e-commerce platforms during peak holiday seasons to steal sensitive customer and parental payment data.
Essential Insurance for Toy Companies
Product Liability Insurance

Design flaws or manufacturing negligence that introduce hazards such as toxic materials or choking risks in children's toys can lead to multi-party lawsuits. Without proper protection, defending these claims in foreign courts may result in significant settlements, high legal fees, and lasting reputational damage.
For instance, Mattel was sued and fined $2.3 million because millions of Barbies contained highly toxic lead paint, posing a risk to children.
Product liability insurance helps mitigate these financial risks by covering legal defence costs, settlements, and compensation awards. This coverage allows your company to manage product liability claims without depleting operating capital, supporting business continuity and consumer trust.
Product Recall Insurance

f a batch of toys is found to be dangerous, an immediate global recall is essential to prevent further harm. However, the logistics can quickly overwhelm a company. Covering recall costs out of pocket, including shipping, public relations, and emergency retail coordination, can strain cash flow and reduce company value.
For example, Hasbro recalled a million of their Easy-Bake Ovens product because it burned children’s fingers. The product recall cost US$10.4 million and drastically hurt their stocks.
Product recall insurance offers crucial financial support for these operations, covering logistics, communications, and PR expenses. This coverage helps prevent recall costs from threatening your business, enabling you to respond quickly to safety issues and protect your brand.
Public Liability Insurance
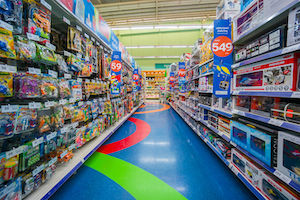
Retail environments, particularly during busy shopping seasons, present increased risks of customer injuries from hazards such as stray toys or unstable displays. If someone is seriously injured on your premises, your business may face legal liability, including lawsuits and significant compensation claims.
Public liability insurance protects your business by covering third-party bodily injury and property damage claims related to your premises or retail activities. This coverage helps prevent unexpected accidents from disrupting your operations or threatening your business’s financial stability.
Property All-Risk Insurance

Unforeseen natural disasters, such as severe monsoon floods or warehouse fires, can quickly destroy essential equipment, storage facilities, and inventory. Without insurance, a company must bear the full cost of repairs and replacements, which can halt operations and revenue.
For example, the Toys R Us roof collapsed due to heavy rain, destroying the store and thousands of products.
Property all-risk insurance covers these expenses, enabling your business to recover quickly. This policy protects your balance sheet from major losses and helps ensure your company remains operational after unexpected disasters
Cyber Insurance

E-commerce toy platforms face increased web traffic during the holidays, making them attractive targets for cybercriminals seeking sensitive credit card and parental data. A significant data breach can result in regulatory fines, forensic investigation costs, loss of customer trust, user attrition, and potential legal claims.
Cyber insurance helps mitigate these financial risks by covering expert consultation, threat removal, data recovery, and required legal notifications. Securing this coverage strengthens your business’s financial resilience against cyber threats and helps protect ongoing revenue.
Why Insurance is Essential for Toy Companies
Protect Operating Capital: It absorbs major expenses from child injury claims, property damage lawsuits, and costly legal defence fees.
Support Business Continuity: Comprehensive coverage minimises cash flow disruption by funding rapid claims resolution and physical asset recovery.
Meet Retail Mandates: Active liability policies satisfy strict international buyer requirements, retail vendor agreements, and import regulations.
Protect Brand Reputation: Proper risk management provides resources to handle consumer safety incidents, product recalls, and digital breaches professionally.
Provide Peace of Mind: Knowing your global product and operational liabilities are fully protected allows your enterprise to focus on creating safe, entertaining toys.
Toy Company Insurance Summary
Insurance Policy | Coverage Provided | Why Businesses Need It |
Product Liability Insurance | Legal defense fees, court settlements, and compensation awards for third-party injury or property damage claims. | To defend against expensive international lawsuits triggered by defective or harmful toys. |
Product Recall Insurance | Financial coverage for logistics, public relations, and communication costs related to retrieving defective items. | To absorb the massive operational expenses of removing dangerous toy batches from global markets. |
Public Liability Insurance | Compensation and legal defense for third-party injuries occurring within physical retail premises. | To manage legal claims and settlements if a customer slips or gets hurt inside a physical toy store. |
Property All-Risk Insurance | Repair and replacement costs for damaged manufacturing equipment, warehouses, and store fixtures. | To recover financially from fires, floods, or natural disasters destroying critical physical assets. |
Cyber Insurance | Funding for data recovery, threat removal, ransom payments, and third-party notification costs following a digital breach. | To survive the heavy financial fallout of hackers stealing sensitive e-commerce customer data. |
Toy Company FAQs
Does product liability insurance cover the cost of recalling a defective toy batch from retail shelves?
No, product liability policies cover only third-party injury and property damage. Toy companies require a product recall insurance extension to manage the physical, logistical, and public relations costs of retrieving defective products.
Are we still covered if a child or parent is injured while shopping in our physical retail store?
Yes, if you have active public liability insurance. This policy covers third-party bodily injury and property damage claims that occur on your business premises or during daily retail operations.
Why do toy retailers need cyber insurance ?
Online toy stores handle large volumes of sensitive customer data and credit card information, increasing their risk of cyberattacks. Cyber insurance covers recovery, forensic investigation, and notification costs in the event of a data breach.
To Learn More about toy insurance and protect your toy company, contactRed Asia Insurance.


Comments